1515 Britannia Road East, Mississauga, ON L4W 4K1

This page is educational — it’s meant to help you understand your options before any conversation about specific products, not to replace that conversation.

Most life insurance falls into one of these two structures — which one fits depends entirely on your goals and timeline.
Coverage designed to last a lifetime, often considered for estate or legacy purposes — see Estate & Legacy Planning.

A foundational layer of protection that can help provide financial support for your loved ones when they need it most — covering things like income replacement, an outstanding mortgage, debt or final expenses.

Coverage designed to provide a financial cushion if you’re diagnosed with a covered critical illness, so you can focus on recovery rather than finances — helping cover time away from work, out-of-pocket treatment costs, or simply the breathing room to slow down and heal.

Protection that can help replace a portion of income if you’re unable to work due to an injury or illness — often the most overlooked area of a financial plan, even though income is usually the foundation everything else, from mortgage payments to savings, is built on.

Supplemental coverage options to help manage everyday health and dental expenses not covered elsewhere — particularly useful for self-employed individuals, contract workers or newcomers to Canada who don’t yet have employer benefits.

Simplified coverage options that may be available without medical underwriting, where applicable and depending on eligibility — often a starting point for those who may not qualify for traditional coverage due to health history.
Availability of specific products depends on current licensing, underwriting and eligibility requirements, and is subject to compliance review. This page is educational and does not guarantee coverage, approval or outcomes.
WHY THIS MATTERS LOCALLY
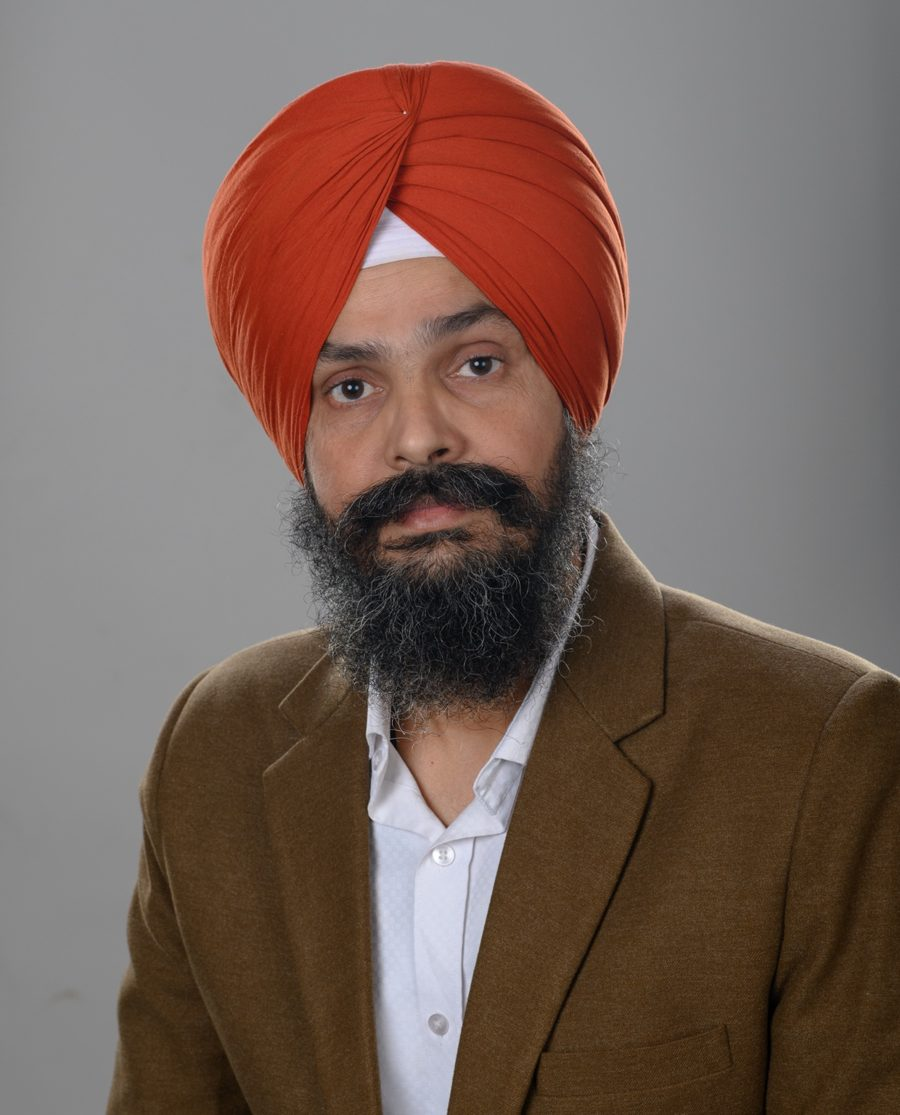
A NOTE FROM JAGDEEP
“My goal isn’t to sell you something — it’s to help you see your financial picture clearly, so you can make the decisions that are right for you and your family.”
Jagdeep Singh Gill — Affiliated with Experior Financial Group Inc.
Do I need all of these types of coverage?
Not necessarily — coverage needs vary by situation, which is exactly what a Financial Check-Up helps clarify.
Is there a medical exam required?
It depends on the product and amount of coverage — some options, like Guaranteed Issue, may not require one.
How long does it take to get covered?
Timelines vary by insurer and product — this is something we can walk through together during your Financial Check-Up.
I already have some coverage through my employer — is that enough?
Employer coverage is often a helpful start but usually ends if you change jobs, which is worth reviewing alongside any personal coverage you may want to keep regardless of employment.
Can I get coverage if I’m new to Canada?
Options depend on individual circumstances such as immigration status and residency — this is reviewed together in a conversation rather than assumed either way.